What Should Bag Importers Know About HS Codes and Duty Rates?
Two bags can look identical in a photograph and carry different duty rates. The difference is not the design or the brand: it is the tariff classification, a ten-digit code that a customs authority uses to decide what the product is and therefore what it costs to import. For importers of PU leather bags, that code drives landed cost, compliance exposure and, in some cases, whether the shipment clears at all.
Classification is also the part of importing most often handled by guesswork. A supplier writes a code on the invoice, the buyer accepts it because it looks plausible, and the shipment clears. Nothing appears wrong until an audit, a reclassification or a retrospective duty demand arrives years later. By then the goods are sold, the supplier relationship has ended, and the liability sits with the importer of record.
Why the code is not clerical
An HS code determines the duty rate, the applicable trade measures, the documentation required, and sometimes the admissibility of the product itself. It is a legal declaration, signed by the importer, not a shipping detail.
Where bags become complicated
Bag classification depends on the outer material, the construction, and in some headings the lining. A bag described as leather may be classified as a plastic article if the outer surface is coated material, and a textile bag with leather trim is generally classified by the textile. These are not rounding errors; they move the product between chapters.
Who carries the risk
Under most Incoterms the buyer is the importer of record and therefore owns the classification. Under DDP the seller may declare, but the underlying facts remain the same, and an incorrect declaration can still surface.
What this article covers
How the HS system is structured, how PU leather bags are classified and where the common errors sit, the difference between bound and applied rates, how landed cost is actually built, valuation rules that change duty, preferential treatment, audits and voluntary disclosure, and what to put into supplier agreements so the code is defensible rather than inherited.
- How the HS System Is Structured
- Classifying PU Leather Bags
- Why Outer Material Decides the Chapter
- Bound, Applied and Preferential Rates
- Building the Landed Cost
- Valuation Rules That Change Duty
- Origin and Preferential Treatment
- Documents That Support the Code
- What Suppliers Get Wrong
- Audits, Reclassification and Disclosure
- Binding Rulings and Advance Certainty
- Building a Classification Control
- Common Classification Mistakes
- How Rates Differ by Destination
- Free Zones and Duty Deferral
- FAQ
How the HS System Is Structured
The Harmonized System is a global nomenclature maintained by the World Customs Organization, and understanding its layers explains why the last digits matter most.
The six-digit core
The first six digits are internationally agreed: chapter, heading and subheading. Every country using the system classifies the same product to the same six digits, which is what makes trade statistics comparable.
National extensions
Beyond six digits, countries add their own subdivisions, usually to eight or ten digits. Duty rates attach at the national level, so two countries can share a six-digit code and apply very different rates.
Chapters relevant to bags
Bags appear mainly in Chapter 42 for leather and composition leather articles, and Chapter 39 for plastic articles, with textile bags in Chapter 63. Moving between these chapters is not a minor adjustment.
| Level | Digits | Set by | Practical effect |
|---|---|---|---|
| Chapter | 2 | WCO | Broad product family |
| Heading | 4 | WCO | Product type |
| Subheading | 6 | WCO | Internationally comparable |
| National line | 8 | National tariff | Duty rate attaches |
| Statistical line | 10 | National tariff | Reporting and measures |
| Explanatory notes | n/a | WCO | Interpretation guidance |
Reading the notes
The General Interpretative Rules and the Explanatory Notes determine how a product is assigned. Rule 3, for example, covers goods that appear to fall in more than one heading, which is exactly the situation for a bag with mixed materials.
Why the last digits carry the risk
Because duty attaches at the national line, an error in the eighth or tenth digit can change the rate even when the first six digits are correct. Most reclassification disputes happen at this level.
Classifying PU Leather Bags
PU leather bags sit at the boundary between two chapters, and the deciding factor is what the outer surface actually is.
The Chapter 42 route
Heading 4202 covers travelling bags, handbags and similar containers with an outer surface of leather, of composition leather, or of patent leather. Where the outer material qualifies, bags fall here.
The Chapter 39 route
If the outer surface is a plastic sheeting material, the bag is generally classified as an article of plastics. Coated textile where the coating is visible can fall here depending on the national tariff interpretation.
Where PU leather lands
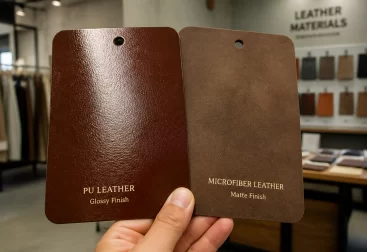
PU leather is a textile or other substrate with a polyurethane coating. Whether it is treated as composition leather, as plastic sheeting, or as coated textile determines the chapter, and different jurisdictions have taken different positions on specific products.
| Outer surface | Likely chapter | Key question |
|---|---|---|
| Genuine leather | 42 | Is the outer surface leather |
| Composition leather | 42 | Does it meet the heading definition |
| PU coated textile, coating visible | 39 or 59 | Is the coating the essential character |
| PU coated textile, textile visible | 63 | Does textile give essential character |
| Uncoated textile | 63 | Textile outer surface |
| Mixed materials | Varies | General Interpretative Rule 3 |
Why identical-looking bags differ
Two bags with the same silhouette can be classified differently because one uses a coated material where the plastic is visible and the other uses a coated textile where the fabric shows through. The appearance to a buyer is similar; the tariff treatment is not.
The lining question
Lining usually does not decide classification, but it can affect a national subheading. It should still be described accurately, because an inaccurate description undermines the whole declaration.
The bag is classified by what it is made of on the outside, not by what it is called in the catalogue.
Why Outer Material Decides the Chapter
The classification logic follows the visible outer surface because that is what the nomenclature specifies, and this has direct consequences for product development.
The visible surface test
Where a material is coated, the question is whether the coating is visible to the naked eye without regard to colour changes caused by the coating. If the coating can be seen, the product is generally treated as coated material.
Composition leather definitions
Composition leather has a specific definition based on leather fibre agglomerated with a binder. A PU-coated textile does not automatically meet it, even when marketing language calls the material leather.
Marketing language versus tariff language
Calling a product vegan leather or PU leather is commercially sensible and tariff-irrelevant. The declaration must describe the material in the terms the nomenclature uses.
| Description used | Tariff relevance | What to declare instead |
|---|---|---|
| PU leather | None on its own | Coated textile or plastic sheeting |
| Vegan leather | None | Material composition and coating |
| Faux leather | None | Substrate plus coating |
| Composition leather | Specific definition | Only if the definition is met |
| Coated textile | Relevant | Coating type and visibility |
| Technical fabric | None | Fibre content and treatment |
Design consequences
Because the material decides the code, a change from one coated substrate to another can change the duty rate mid-season. That is a commercial risk worth modelling before the change, not after the first shipment.
Sample and testing implications
Where classification is disputed, evidence about the material may be required: composition, coating weight, and whether the coating is visible. Suppliers should be able to provide this.
Bound, Applied and Preferential Rates
Duty rates are not a single number, and knowing which rate applies prevents both overpayment and surprise demands.
The bound rate
The bound rate is a ceiling a country has committed to in the WTO. It cannot normally be exceeded, which provides a level of predictability.
The applied rate
The applied rate is what is actually charged, and it is frequently lower than the bound rate. The applied rate is the one that matters for costing.
The preferential rate
A preferential rate applies where a trade agreement covers the goods and origin is properly evidenced. It can be zero, and it requires documentation rather than assumption.
| Rate type | Who sets it | When it applies | Evidence needed |
|---|---|---|---|
| Bound | WTO commitment | Ceiling, rarely charged | None |
| Applied | National tariff | Default for all imports | Classification only |
| Preferential | Trade agreement | Qualifying origin | Origin proof |
| Anti-dumping | Trade remedy | Named products and origins | Case reference |
| Quota rate | National measure | Within quota volume | Quota allocation |
| Suspension | National measure | Temporary relief | Legal reference |
Additional measures
Beyond duty, specific measures may apply: anti-dumping duties on certain origins, safeguard measures, or additional tariffs. These attach to the code, which is another reason the code matters.
Rate changes over time
Applied rates and trade measures change. A rate confirmed last year is not a guarantee for this year, and costings built on stale rates understate landed cost.
Checking the current rate
Confirm the rate against the destination customs tariff for the specific national code and the specific origin, at the time of shipment. This is a five-minute check that prevents a five-figure surprise.
Building the Landed Cost
Duty is one line in a landed cost, and building the full structure shows where classification errors actually bite.
The components
Goods value, freight, insurance, duty, import VAT or sales tax, customs brokerage, terminal handling, inland transport and any additional measures. Duty is calculated on a value that usually includes freight and insurance.
Why freight affects duty
Where duty is assessed on a CIF basis, freight and insurance are part of the dutiable value. A high freight quote therefore raises duty as well as freight cost, which is often overlooked when comparing forwarders.
The VAT recovery question
Import VAT may be recoverable depending on the buyer’s registration status. Where it is recoverable it is a cash flow item, not a cost; where it is not, it belongs in the landed cost.
| Cost line | Dutiable | Recoverable | Note |
|---|---|---|---|
| Goods value | Yes | No | Basis of duty |
| International freight | Usually | No | Raises duty where CIF basis |
| Insurance | Usually | No | Small but dutiable |
| Duty | No | No | A cost |
| Import VAT | No | Often | Cash flow only if recoverable |
| Brokerage and handling | No | No | Service costs |
Calculating per unit
Landed cost per unit is what determines margin, and it should include every line above divided by sellable units, not cartons received. Short shipments and damage should not be spread silently across the total.
The comparison trap
Two suppliers quoting similar unit prices can produce very different landed costs if one uses a material classified at a higher rate. Comparing unit price without duty is comparing incomplete numbers.
Valuation Rules That Change Duty
Duty is charged on value, so the valuation method matters as much as the rate.
Transaction value
The primary method is the price actually paid or payable, adjusted for specified items. Most imports use this method, and most disputes concern what should be added.
Assists and free materials
Materials, tooling or moulds supplied free or at reduced cost by the buyer must generally be added to the value. Bag importers who supply hardware or labels to a factory often overlook this obligation.
Royalties and licence fees
Royalties related to the imported goods and paid as a condition of sale are generally dutiable. Brand licensing arrangements therefore have a customs consequence.
Related party transactions
Where buyer and seller are related, the transaction value is accepted only if it approximates an arm’s length price. Transfer pricing and customs valuation are separate regimes that must both be satisfied.
| Item | Add to value | Reason |
|---|---|---|
| Buyer-supplied hardware | Yes | An assist |
| Buyer-supplied moulds | Yes, apportioned | An assist |
| Brand royalty | Usually | Condition of sale |
| Inland freight after import | No | Post-importation |
| Buying commission | No | Distinct from selling commission |
| Selling commission | Yes | Part of price paid |
Under-declaration risk
Declaring a lower value to reduce duty is a compliance offence, and the exposure includes duty, penalties and seizure. The importer of record carries it, not the supplier who suggested it.
Origin and Preferential Treatment
Origin is separate from classification, and getting one right without the other produces no benefit.
Non-preferential origin
Non-preferential origin determines marking, statistics and any trade measures. It applies regardless of trade agreements.
Preferential origin
A preferential claim requires the goods to meet the rules of origin in the relevant agreement, usually expressed as a change in tariff classification or a regional value content test, and to be supported by a valid origin document.
Why bag supply chains fail origin tests
Bags are assembled from materials sourced across several countries. If the coating or the substrate originates outside the agreement area, the change in tariff classification test may not be met, and the preferential rate is unavailable.
| Test type | What it requires | Bag-specific issue |
|---|---|---|
| Change in tariff classification | Non-originating inputs change heading | Coating may not change heading |
| Regional value content | Minimum regional value share | Imported material raises foreign share |
| Specific process rule | Defined manufacturing operation | Cutting and sewing may qualify |
| Wholly obtained | Entirely from one country | Rarely met for bags |
| De minimis | Tolerance for non-originating inputs | Limited, varies by agreement |
| Direct consignment | Transport through qualifying countries | Transhipment can break the claim |
The documentation requirement
A preferential rate requires an origin declaration or certificate, issued by the right party, in the right format. A supplier statement that goods are local is not sufficient.
Claiming and proving
Preferential claims can be verified after the fact. Where the underlying records do not support the claim, the duty becomes payable with interest, which turns a saving into a liability.
Documents That Support the Code
A classification is only as good as the evidence behind it, and that evidence must exist before the question is asked.
The commercial invoice description
The description should state the material composition and construction clearly enough to support the code. Generic descriptions invite examination and undermine the declaration.
Material specifications
Coating type, substrate fibre content and coating visibility are the facts that decide the chapter for coated materials. These should be documented at development stage.
Technical data sheets
Supplier data sheets describing the material provide contemporaneous evidence. Where a dispute arises, a data sheet dated before the import is far stronger than a statement produced afterwards.
| Document | Supports | Timing |
|---|---|---|
| Commercial invoice | Description and value | At shipment |
| Material data sheet | Composition and coating | At development |
| Bill of materials | Component origin | At development |
| Origin certificate | Preferential claim | At shipment |
| Test reports | Material properties | Before first import |
| Classification record | Reasoning and sources | Before first import |
The classification record
Keep a written note of the code chosen, the reasoning, the sources consulted and the date. In an audit, a documented process is treated very differently from an undocumented one.
What Suppliers Get Wrong
Suppliers provide codes routinely, and those codes are frequently copied from an earlier shipment rather than determined for the product.
The inherited code
A factory that has shipped similar bags may reuse the code without checking whether the material of this order differs. The buyer then declares a code that does not match the goods.
The convenient code
Where one code carries a lower rate, there is commercial pressure to use it. That pressure is a compliance risk for the importer, not the supplier.
Confusing product name with material
Suppliers often describe goods in marketing terms. The tariff needs material terms, and the translation is the importer’s responsibility.
| Supplier statement | Risk | What to request |
|---|---|---|
| Same code as last order | Material may differ | Code confirmed per order |
| Code on invoice only | No reasoning | Written classification basis |
| PU leather description | Tariff-irrelevant wording | Substrate and coating detail |
| Lowest-rate code | Misclassification | Independent verification |
| Origin by assertion | Preference invalid | Origin declaration |
| Silence on assists | Undervaluation | Declared assist value |
A code supplied on an invoice is a convenience, not a classification decision. The decision belongs to the importer.
Contractual protection
Require the supplier to state the material composition and to notify any change in material or construction. That notification clause is what allows the buyer to re-check the code before the change ships.
Audits, Reclassification and Disclosure
Customs authorities audit after the fact, and the way an importer responds determines whether the outcome is a correction or a penalty.
How audits start
Post-clearance audits may be selected by risk profile, by a pattern in declarations, or at random. Volumetric bag imports with inconsistent descriptions attract attention.
The retrospective demand
Where a code is found to be wrong, duty is usually demanded for past entries within a limitation period, with interest. For a high-volume importer this can be a significant sum.
Voluntary disclosure
Many jurisdictions provide reduced penalties where an error is disclosed voluntarily before discovery. The benefit depends on acting early and on the disclosure being complete.
| Scenario | Typical outcome | Mitigation |
|---|---|---|
| Error found in audit | Duty, interest, penalty | Documented process |
| Voluntary disclosure | Reduced penalty | Act before notification |
| Supplier code wrong | Importer liable | Independent verification |
| Undervaluation found | Duty and penalty | Correct assist reporting |
| Invalid origin claim | Duty plus interest | Verify rules of origin |
| Repeat errors | Escalated penalty | Fix the control, not the entry |
Correcting versus contesting
Where the authority’s position is defensible, correcting is usually cheaper than contesting. Where the product genuinely falls in the declared heading, a reasoned response with evidence is appropriate.
Binding Rulings and Advance Certainty
Certainty can be purchased in advance, and for a product with a borderline classification that is usually worth doing.
What a binding ruling provides
A written decision from the customs authority on how a specific product will be classified, valid for a defined period and binding on the authority in most jurisdictions. It converts an interpretation into an instruction.
When to request one
When the material is borderline between chapters, when the duty difference is material, when volumes justify the effort, or when a supplier’s code cannot be independently supported.
What the application needs
A full description, material composition, construction details, samples or photographs, and often test data. Incomplete applications produce narrow or unfavourable rulings.
| Factor | Favours a ruling | Favours relying on process |
|---|---|---|
| Duty rate difference | Large | Negligible |
| Material ambiguity | High | Low |
| Order volume | High | Low |
| Repeat shipments | Regular | One-off |
| Design stability | Stable | Frequently changing |
| Number of destinations | One or two | Many |
The limitation to understand
A ruling applies to the product described. Change the material or construction and the ruling may no longer cover it, which is why material change notification matters.
Building a Classification Control
The objective is not a perfect code for one shipment but a repeatable process that produces defensible codes.
Who owns classification
Assign responsibility explicitly, usually to the person who signs the customs declaration or to a named compliance role. Diffuse responsibility is how inherited codes survive.
The classification file
For each product, record the code, the reasoning, the material evidence, the ruling if any, and the date of the last review. This is the artefact that makes an audit manageable.
The change trigger
Any change in material, construction, lining or hardware should trigger a re-check. This is a short review, not a full project, and it is where most risk is prevented.
| Control element | What it prevents | Effort |
|---|---|---|
| Named owner | Unclear accountability | Low |
| Classification file | Undocumented decisions | Medium |
| Material change trigger | Stale codes | Low |
| Supplier declaration | Inherited codes | Low |
| Annual rate review | Outdated costings | Low |
| Broker briefing | Entry errors | Low |
Briefing the broker
A customs broker applies the code provided. Providing the classification file and material data lets the broker challenge an inconsistency before the entry is filed.
Reviewing entries
Spot-check cleared entries against the classification file. Discrepancies between what was intended and what was declared are common and cheap to fix early.
Common Classification Mistakes
Most errors repeat across importers, and recognising them is faster than learning from an audit.
Accepting the supplier’s code
The single most common error. The code reflects the supplier’s convenience or habit rather than a determination for the goods.
Classifying by product name
Names are commercial. Classification depends on material and construction, and the two rarely align for coated materials.
Ignoring assists
Buyer-supplied hardware, labels or tooling that are not added to the customs value produce an undervaluation, which is a separate offence from misclassification.
| Mistake | Consequence | Correction |
|---|---|---|
| Inherited supplier code | Wrong duty, audit exposure | Independent determination |
| Classifying by name | Wrong chapter | Classify by material |
| Ignoring assists | Undervaluation | Add to declared value |
| Assuming origin | Invalid preference | Verify rules of origin |
| Using stale rates | Understated landed cost | Check current tariff |
| No documented reasoning | Weaker audit position | Keep a classification file |
Treating the code as fixed
A material change can move the product between chapters. Codes are product-specific and should be revisited when the product changes.
Assuming the broker is responsible
The broker files on the importer’s instructions. Legal responsibility for the declaration rests with the importer of record.
How Rates Differ by Destination
The same bag can carry very different duty in different markets, and the difference comes from the national tariff rather than the six-digit code.
Why the same code produces different rates
Because duty attaches to the national tariff line, each destination sets its own rate for the same internationally agreed subheading. A bag classified identically at six digits can be duty-free in one market and dutiable in another.
What else varies by market
Beyond the rate, markets differ in documentation requirements, labelling rules, restricted substances, and the treatment of coated materials. A specification that clears one market may require additional evidence in another.
Consequences for range planning
Where one range is sold into several markets, landed cost should be calculated per market rather than averaged. An average hides the market where the margin is thinnest.
| Variable | Set by | Effect on importer |
|---|---|---|
| Duty rate | National tariff | Changes landed cost per market |
| VAT or sales tax | National tax law | Cash flow or cost |
| Documentation | Customs authority | Clearance speed |
| Labelling rules | Consumer or customs law | Compliance before import |
| Restricted substances | Product regulation | Testing before shipment |
| Origin requirements | Trade agreements | Preferential rate access |
Checking before quoting
Confirm the rate and the documentation set for each destination before quoting a retail price. Discovering a requirement after the goods are ordered leaves few options other than absorbing the cost.
Multi-market allocations
Where one production run serves several markets, allocate duty by destination rather than blending it. Blended duty produces pricing that is too high in one market and unprofitable in another.
Free Zones and Duty Deferral
Duty timing can be managed legitimately, and for importers with storage or re-export activity the tools are worth understanding.
Free zones and bonded warehouses
Goods held in a free zone or bonded warehouse are generally not subject to duty until they enter the customs territory. That defers the cash outflow and allows inspection before the duty is committed.
When deferral helps
Deferral is most useful where goods are stored before sale, where part of a consignment may be re-exported, or where cash flow is tight relative to order size.
The conditions
Deferral requires authorisation, record-keeping and physical controls. Goods must be accounted for, and removing them without declaration creates a liability that is treated seriously.
| Arrangement | Duty point | Main condition |
|---|---|---|
| Direct import | On entry | Declaration at clearance |
| Bonded warehouse | On release | Authorisation and records |
| Free zone | On entry to territory | Zone controls |
| Inward processing | On finished goods | Process and re-export rules |
| Re-export | Not applicable | Goods leave unaltered |
| Transit | At destination | Transit document intact |
The record-keeping burden
Deferral shifts effort from cash to administration. Without reliable stock records, the arrangement becomes a compliance exposure rather than a benefit.
FAQ
What HS code do PU leather bags usually fall under?
It depends on the outer surface. Genuine or composition leather bags generally fall in Chapter 42. Where the outer surface is plastic sheeting the bag is usually classified in Chapter 39, and where textile gives the essential character it falls in Chapter 63. A PU-coated material must be assessed on whether the coating is visible.
Can I rely on the HS code my supplier provides?
No. Supplier codes are frequently inherited from earlier shipments and may not reflect the material of the current order. The importer of record is legally responsible for the declaration, so the code should be verified independently before the first shipment.
Why do two similar bags have different duty rates?
Because classification follows the material rather than the design. A bag with a visible plastic coating and a bag with a visible textile surface can fall in different chapters even when the silhouette is identical, and duty attaches at the national tariff line.
What is the difference between bound and applied duty rates?
The bound rate is the ceiling committed in the WTO and is rarely charged. The applied rate is what customs actually charges and is the figure to use in costing. Where a trade agreement applies and origin is proven, a preferential rate may reduce it further.
Does freight affect how much duty I pay?
Often yes. Where duty is assessed on a CIF basis, international freight and insurance form part of the dutiable value. A higher freight quote therefore increases duty as well as transport cost, which matters when comparing forwarders.
Do buyer-supplied components affect customs value?
Yes. Hardware, labels, tooling or moulds provided free or at reduced cost are generally treated as assists and must be added to the declared value. Omitting them creates an undervaluation separate from any classification issue.
How do I claim a preferential duty rate?
The goods must meet the rules of origin in the relevant agreement and the claim must be supported by a valid origin document. For bags assembled from materials sourced in several countries, the change in tariff classification test may fail, so the rules should be checked before assuming the saving.
What happens if customs disagrees with my classification?
Duty is typically demanded for past entries within a limitation period, with interest, and a penalty may apply. Where an error is identified internally, a voluntary disclosure before notification often reduces the penalty substantially.
Is a binding ruling worth requesting?
It is worth it where the material is borderline, the duty difference is material and volumes are significant. A ruling converts an interpretation into a written decision, though it applies only to the product as described and stops covering the goods if the material changes.
Who is responsible if my broker files the wrong code?
The importer of record remains legally responsible for the accuracy of the declaration. The broker applies instructions provided, which is why supplying a documented classification file and material data is the importer’s protection.
How often should a classification be reviewed?
At minimum when the material or construction changes, and periodically for rate changes and trade measures. A short annual review plus a change trigger covers most risk without significant effort.
Does the lining of a bag affect classification?
Usually the outer surface determines the chapter, so lining rarely decides it. Lining can still affect a national subheading, and it should be described accurately because an inaccurate description weakens the whole declaration.
Need the material data behind a defensible HS code?
Send your destination market and product specification to info@gionar.com and we will provide the material composition, coating details and construction data your broker needs to classify PU leather bags correctly, along with the documentation that supports the declaration.